If you have owned your home for a few years, you are likely sitting on a goldmine without even realising it. With property prices rising significantly over the last two decades, the gap between what your home is worth and what you owe the bank has likely widened. This gap is called equity. But for many Australians, this wealth is doing absolutely nothing to help them prepare for the future.
In the financial world, this is known as "lazy equity."
Equity increases in two ways: as you pay down your mortgage and as the value of your property rises. However, if that equity simply sits in your property, it isn't generating income or growth for your future retirement. It is static.
As Adam Duster from Oli Property explained in a recent webinar, understanding how to mobilise this equity is the key to shifting from simply being a homeowner to becoming a property
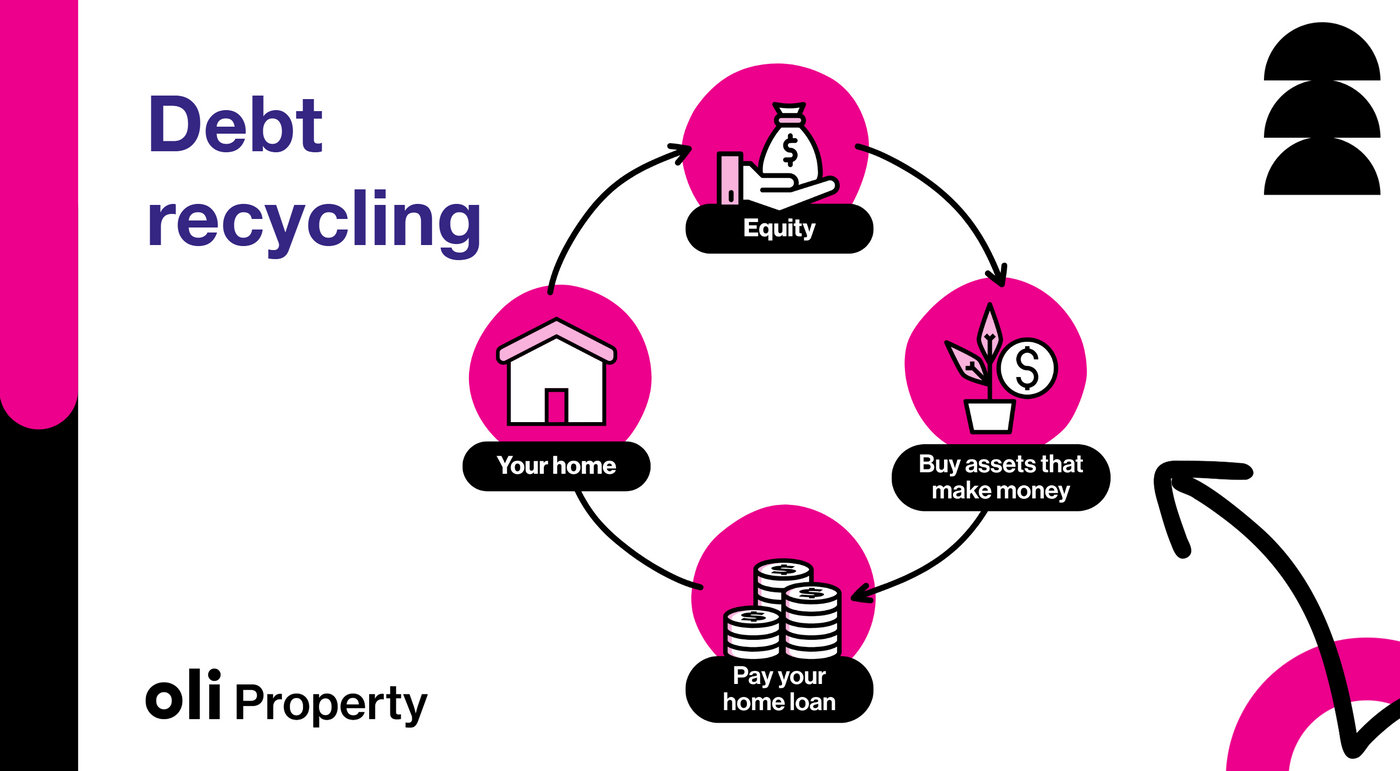
The process of unlocking this equity allows you to purchase an income-generating asset without needing to save a massive cash deposit from your wages. This strategy is often referred to as "debt recycling".
Here is the step-by-step process:
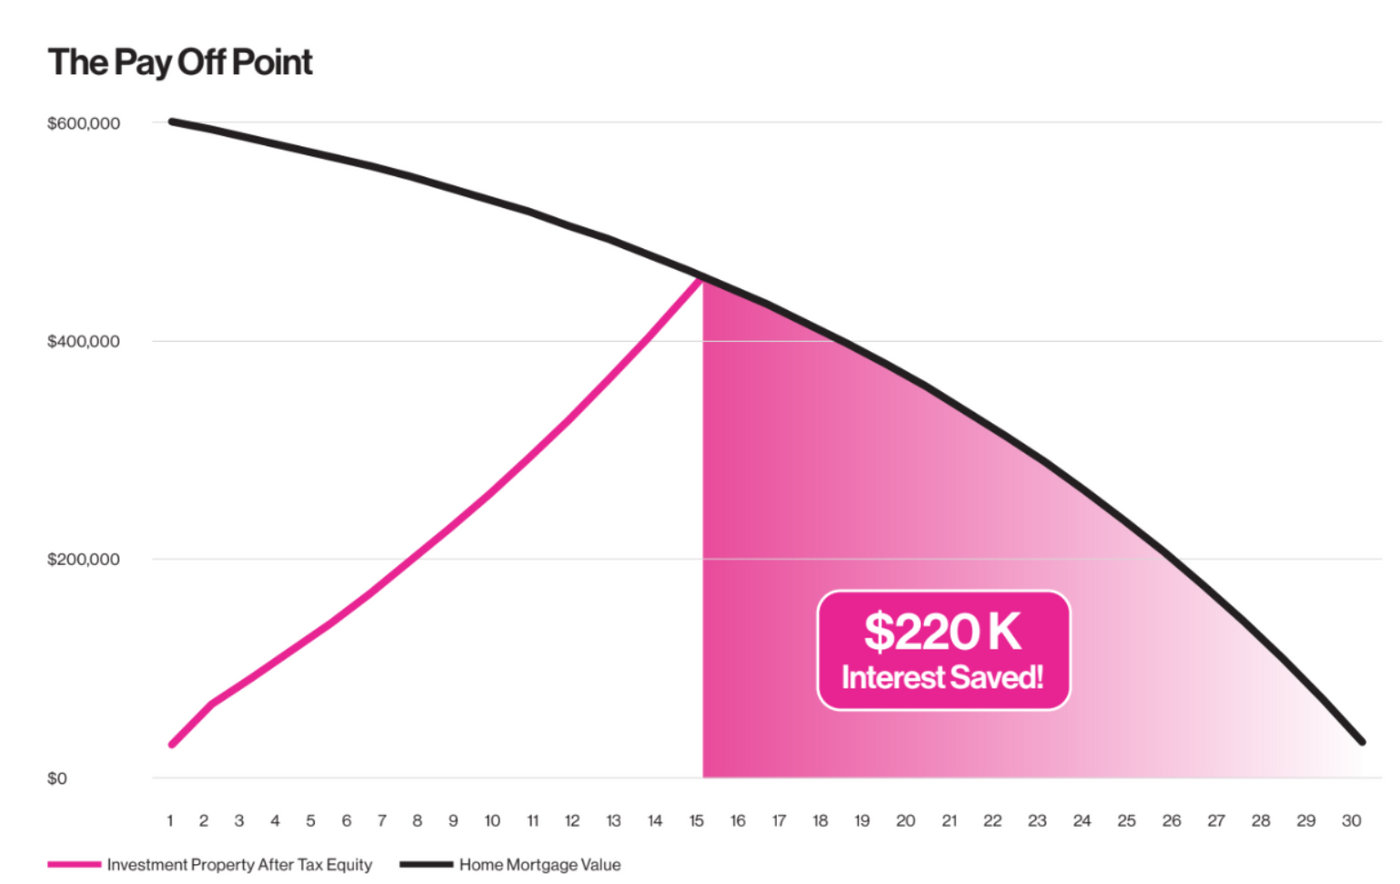
To illustrate the power of this strategy, let’s look at a couple who have made the decision to invest in property. Like many, they had a $600,000 home loan.
Instead of just chipping away at it, they used $100,000 of equity to fund the deposit and costs for a $600,000 investment property.
The biggest hurdle to unlocking lazy equity is often fear or emotional decision-making. But not making a decision and taking the step is also a big risk to your retirement.
To make this strategy work, you must treat your property decisions as business decisions, focusing on infrastructure, population growth, and rental returns rather than personal taste.
A simple introduction to how property may help you clear debt before you stop working, and what that depends on. General information, no guarantees.
Watch the webinarIt is not too late. Australians in their 40s and 50s who know property could support retirement but are not sure how to start.
Explore this path →A Property Investment Specialist can walk you through how these changes relate to your goals, your finances and your timeline.
Our network


Research led by Matt Bell, Chief Economist, Oliver Hume Property Group. 4,800 suburbs, trusted by government and ASX 200 companies.
Oli Property is part of Oliver Hume Property Group, in Australian property since 1954. By signing up you agree to receive the quarterly report and related emails from Oli Property. General information only. Privacy policy


