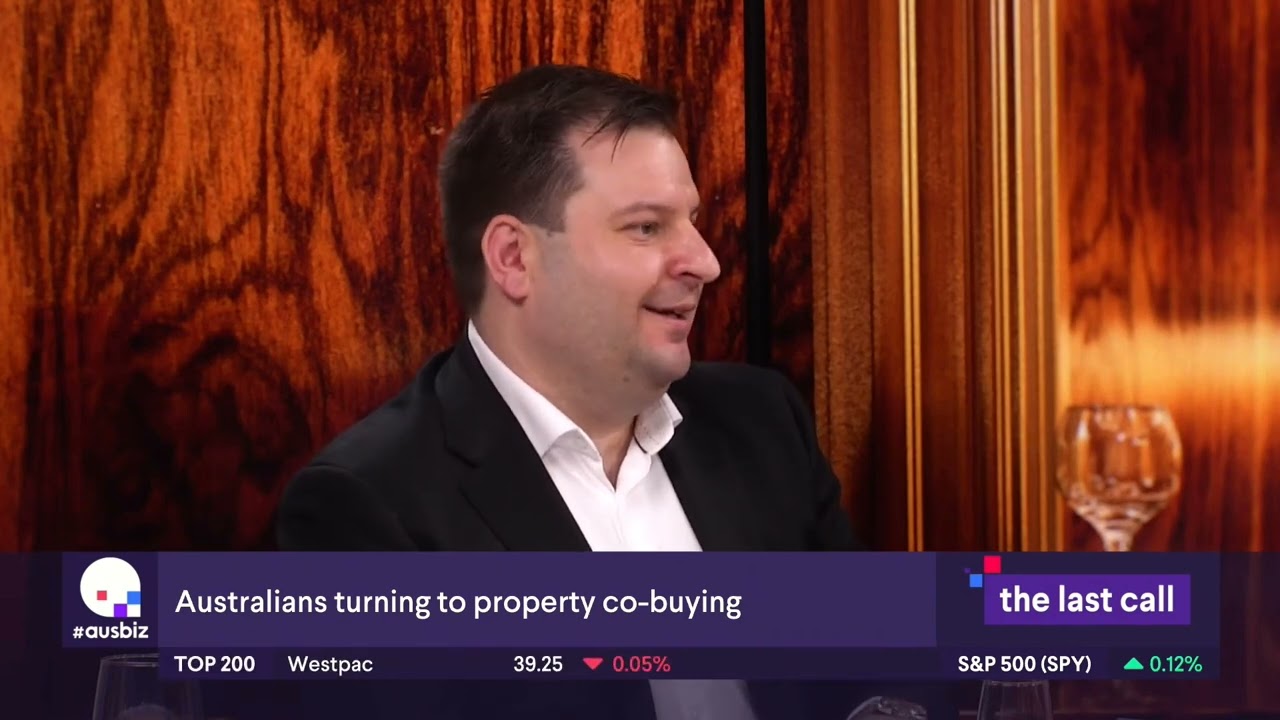
Appearing on AusBiz last Friday, Adam from Oli Property highlighted a growing trend among Australians turning to co-buying as a strategic response to housing affordability challenges.
We’re seeing in the Melbourne market at the moment that there are cash flow positive properties, even under five hundred thousand dollars, which was almost unheard of since the start of COVID.
Melbourne is emerging as a hot spot again. While our research is national, we’ve seen places such as Brisbane, Adelaide, and Perth boom over the last five years. It’s been great to see investors who got in early take advantage of that growth.
However, Melbourne has remained largely stagnant, and we believe it holds strong potential for future growth, particularly as it is expected to become Australia’s largest city by 2032.
By co-buying with your kids, you can help first home buyers secure a deposit faster, share the loan and ongoing costs, and get their foot in the property market sooner. It’s a smart way to build wealth as a family and make homeownership more achievable for the next generation.
Co-buyers can also take comfort knowing that the necessary legal protections are in place, offering flexibility should their circumstances or intentions change.
For those considering co-investment, perhaps purchasing with a friend or family member, renting out the property initially can be a strategic approach. This allows investors to capitalise on growth before deciding whether to occupy the property later in life.
You don’t need to invest where you live, and it’s important to take emotion out of investment decisions, whether it’s co-investing or individual property ownership.
Investment can be challenging because people often approach it emotionally. Many investors believe the best property is within five kilometres of their home. However, the type of property you invest in doesn’t necessarily have to be one you’d live in yourself. The key question is: will this asset create capital growth and support your long-term financial goals?
We often hear questions about negatively and positively geared properties. The reality is, you can pursue either, or a combination of both, depending on your financial goals.
Some investors prefer positively geared assets to generate immediate income, while others choose negative gearing to take advantage of Australia’s generous tax incentives. Ultimately, every investor’s situation is different, and the right strategy depends on individual objectives and timelines.
Economists, including Matt Bell, have noted that interest rates may see only one more cut in the near term. Despite this, demand remains strong across the property market.
Our long-term research (10–15 years) shows a growing scarcity of land in Australia’s capital cities. When supply becomes constrained and population growth remains high, prices tend to rise.
Given this outlook, we believe the property market continues to show solid potential for growth, particularly in Melbourne, which is evolving into a more high-rise-focused urban centre rather than the traditional sprawling city it once was.
The team at Oli Property can help you research, plan, and structure your purchase to meet your goals. Contact Oli Property today to learn how co-buying could help you achieve your property ambitions.
How the equity in your home could help fund an investment property, and what to check before you use it. General information, no guarantees.
Get the free ebookEarning well, thinking long term. Professionals who own their first home and want to build wealth while time is on their side.
Explore this path →A Property Investment Specialist can walk you through how these changes relate to your goals, your finances and your timeline.
Our network


Research led by Matt Bell, Chief Economist, Oliver Hume Property Group. 4,800 suburbs, trusted by government and ASX 200 companies.
Oli Property is part of Oliver Hume Property Group, in Australian property since 1954. By signing up you agree to receive the quarterly report and related emails from Oli Property. General information only. Privacy policy


