
Retirement is closer than it used to feel, and you want to make the most of the years ahead. For many Australians in their 40s and 50s, property investment is a strategy worth understanding as part of broader retirement planning.
Many clients start this conversation in their late 40s and build a clear plan from there. Calm guidance, no urgency. You set the pace.
Property is one tool in a retirement planning toolkit, not a replacement for others. What makes it worth understanding is the combination of rental income potential, capital growth over time, and the ability to use existing equity to build a second asset.
A stability-focused approach may suit this stage of life: properties with consistent rental demand, low maintenance requirements, and locations supported by long-term infrastructure and population growth. Steady outcomes. Not speculation.
People at this stage have specific concerns. They want to use their home equity carefully, without taking on more than they are comfortable with. Most want calm, honest guidance from people who know the subject well. Our process is built around clarity, not urgency.
Whether property suits your retirement plan depends on your equity, borrowing capacity, income and goals. A licensed financial adviser is the right person to assess this. We fit research-backed property to the strategy that suits you.
We take property investment apart and explain it clearly. You will understand what is happening and why before anything is decided.
New, low-maintenance properties selected for rental demand and long-term suitability, supported by the Oliver Hume Property Group's Residential Outlook. All scenarios are general illustrations only.
We have worked with many Australians who started investing in their 40s and 50s. Knowing what works, what to watch for and what questions to ask is part of every conversation.
Watch it at your own pace. When you are ready to talk it through, Cam and Adam are here.
A simple introduction to how property may help you clear debt before you stop working, and what that depends on. General information, no guarantees.
Watch the webinar
Not necessarily. Many Australians start their investment property journey in their 40s and 50s. The key considerations are borrowing capacity, existing equity, income and time horizon. A licensed financial adviser can help you assess whether it suits your position.
It is possible to purchase property through a self-managed superannuation fund, under specific conditions. It is a complex area with strict regulatory requirements and significant penalties for mismanagement. Not suitable for everyone, and specialist advice is essential.
Properties with strong rental demand, low maintenance requirements and locations with long-term infrastructure growth tend to suit a stability-focused strategy. New properties can also offer capital gains tax and depreciation benefits worth discussing with your accountant.
Property investment works alongside super and other savings, not as a substitute. Your financial adviser is best placed to help you understand how these elements interact in your specific situation.
You set the pace. Our process gives you time to think before you commit to anything.
If you are younger and focused on building wealth while renting, our rentvesting page covers that path.
A conversation about where you are and what a realistic plan might look like. No decisions on the call.
Book your free discovery callOur network


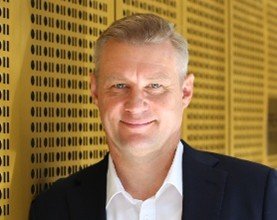
Research led by Matt Bell, Chief Economist, Oliver Hume Property Group. 4,800 suburbs, trusted by government and ASX 200 companies.
Oli Property is part of Oliver Hume Property Group, in Australian property since 1954. By signing up you agree to receive the quarterly report and related emails from Oli Property. General information only. Privacy policy


