If you bought your investment property before 12 May 2026, nothing changes for it. The change is about what you buy next. From 1 July 2027 a loss on an established property can no longer offset your salary and the 50% CGT discount goes. New builds keep both. That is why investors who have only ever bought established are now looking at new, and why we built a toolkit for exactly that move.
Oli Property, Property Tax Changes guide, May 2026, worked example. 47% marginal rate including Medicare levy. Sale scenario assumes 2% CPI and a $400,000 gain; at 6% CPI the sale outcomes are equal and the new build is still ahead on the refunds received while holding. General information, not tax advice.
Three documents, free, by email: the 2026 rules with the $800,000 worked example, a 12-point off-the-plan checklist written for investors who have only bought established, and a step-by-step plan for making the switch. We will also tell you where the worked example project is.
General information only, not tax or financial advice. Confirm your position with a registered tax agent. We do not sell your details.
m10-nat-gearing
National
wealth-builder
melbourne-10km
2026-27 Federal Budget, 12 May 2026, as summarised in the Oli Property Property Tax Changes guide. Your position depends on the final legislation and your circumstances; confirm it with a registered tax agent.
| Factor | Established, bought after 12 May 2026 | New build |
|---|---|---|
| Loss against salary | No. Losses only offset rent from the same property, or carry forward. | Yes. A $15,000 loss returns about $7,050 at 47%. |
| Depreciation | Minimal. Second-hand fittings cannot be claimed. | Building and fittings, in full. |
| When rates rise | You carry the whole increase. | Up to 47% of the increase comes back as refund. |
| Scenario | Established | New build |
|---|---|---|
| Low inflation, 2% CPI | Tax about $150,400 | Tax about $94,000 |
| Elevated inflation, 6% CPI | Tax about $28,200 | Tax about $28,200, plus the refunds already received |
Oli Property, Property Tax Changes guide, May 2026. Both properties bought in June 2026 for $800,000 and sold for $1,200,000; 47% marginal rate. Illustrative only.
Six things that work differently, and what the toolkit does about each.

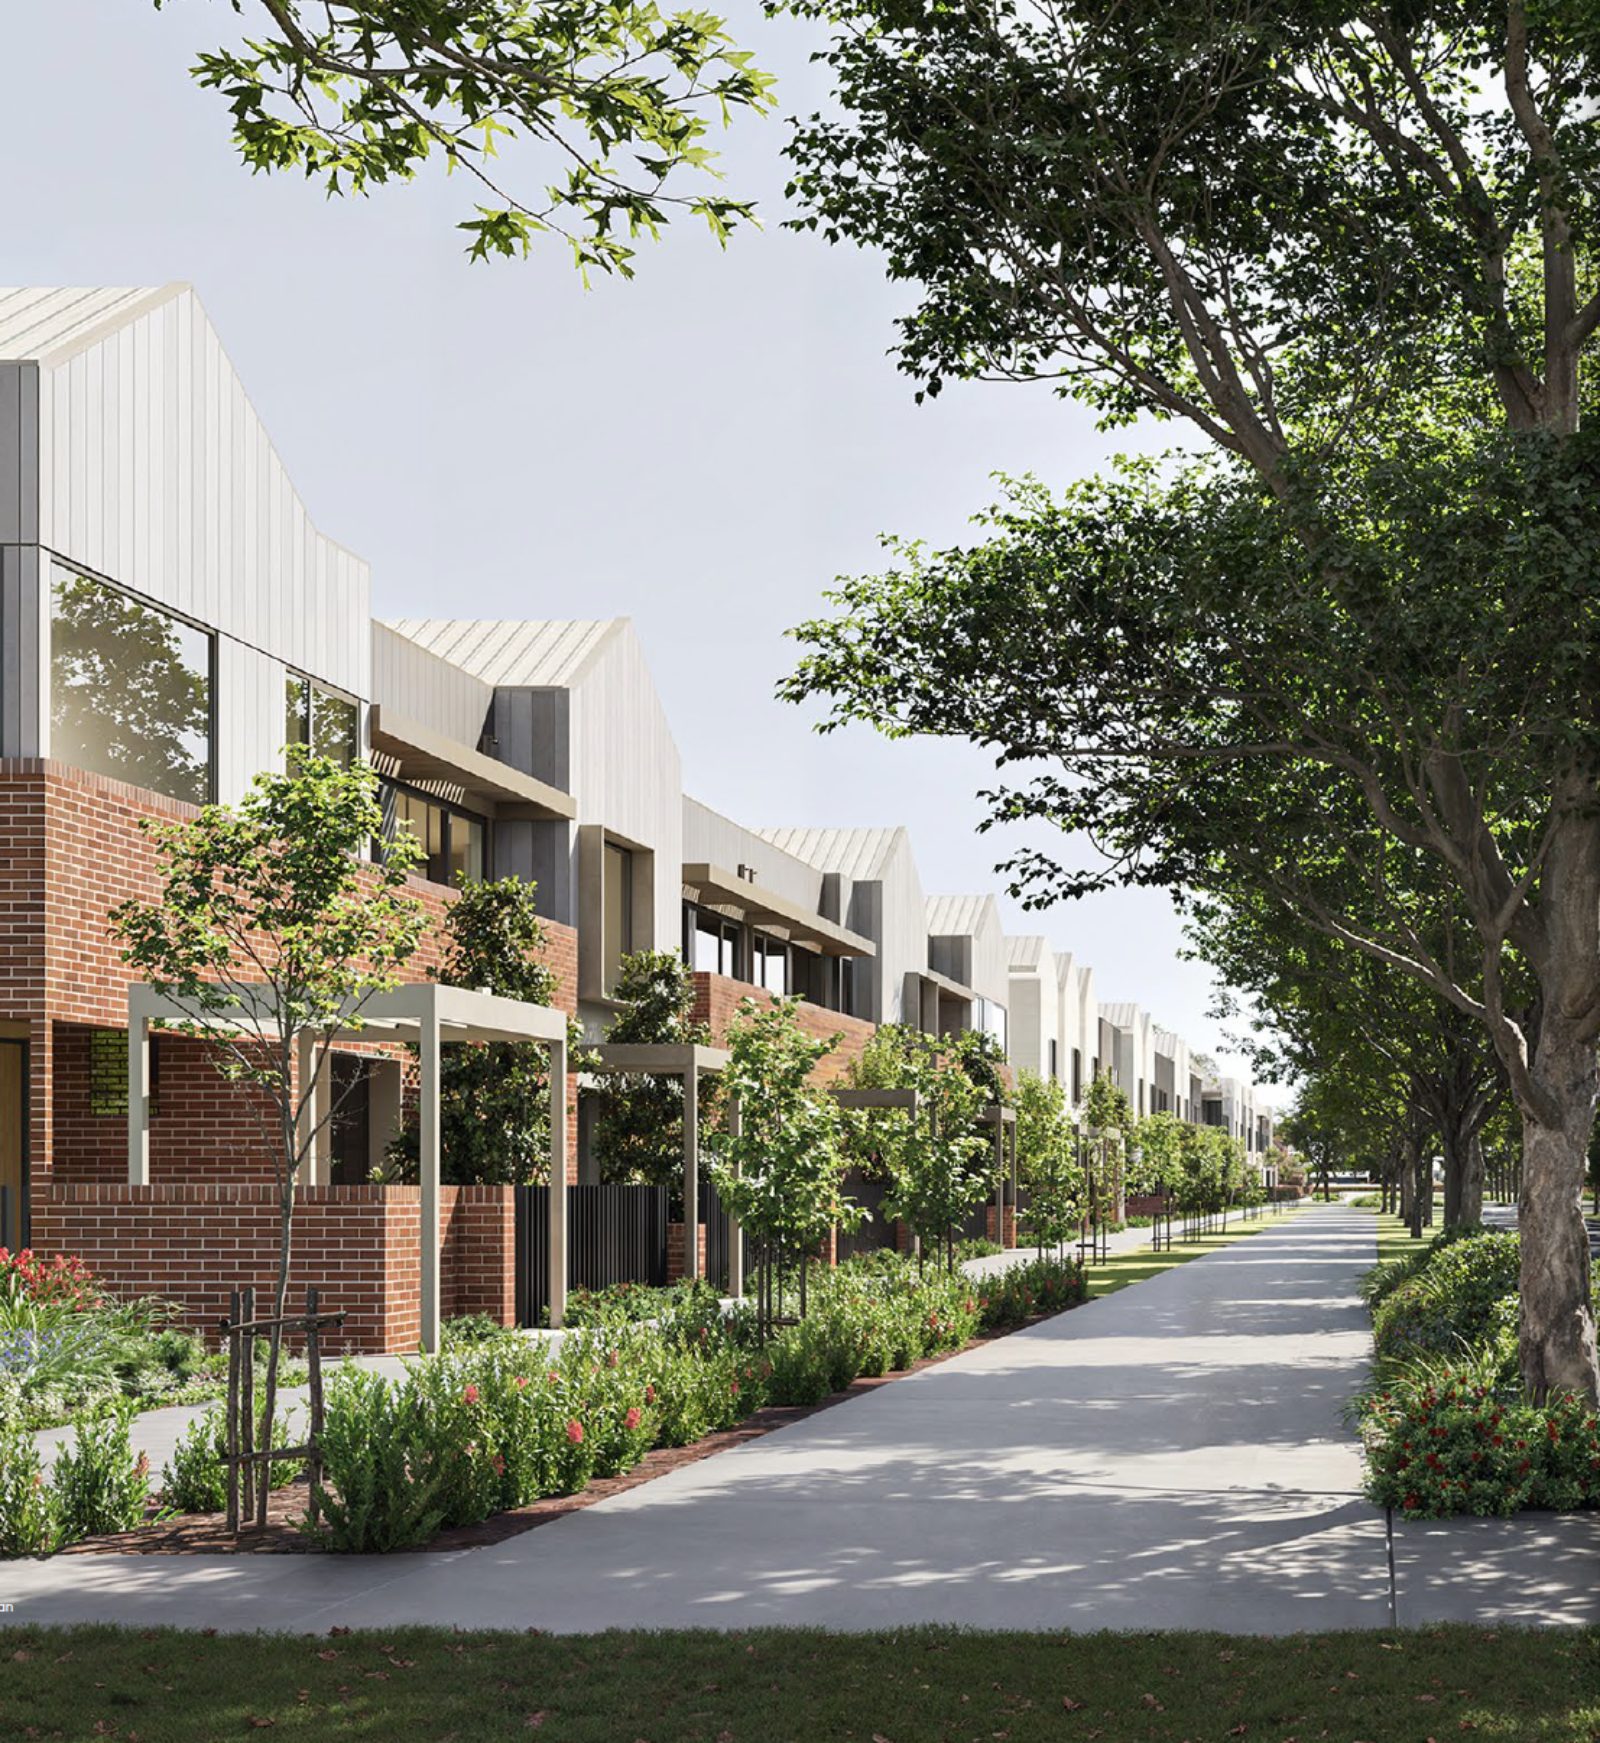
Most new precincts are built on the city fringe. This one sits inside a gazetted comprehensive development plan: 66 hectares of former industrial land 10km from the CBD, with a new town centre, parks and streets funded as part of the plan. We name it when you enquire.
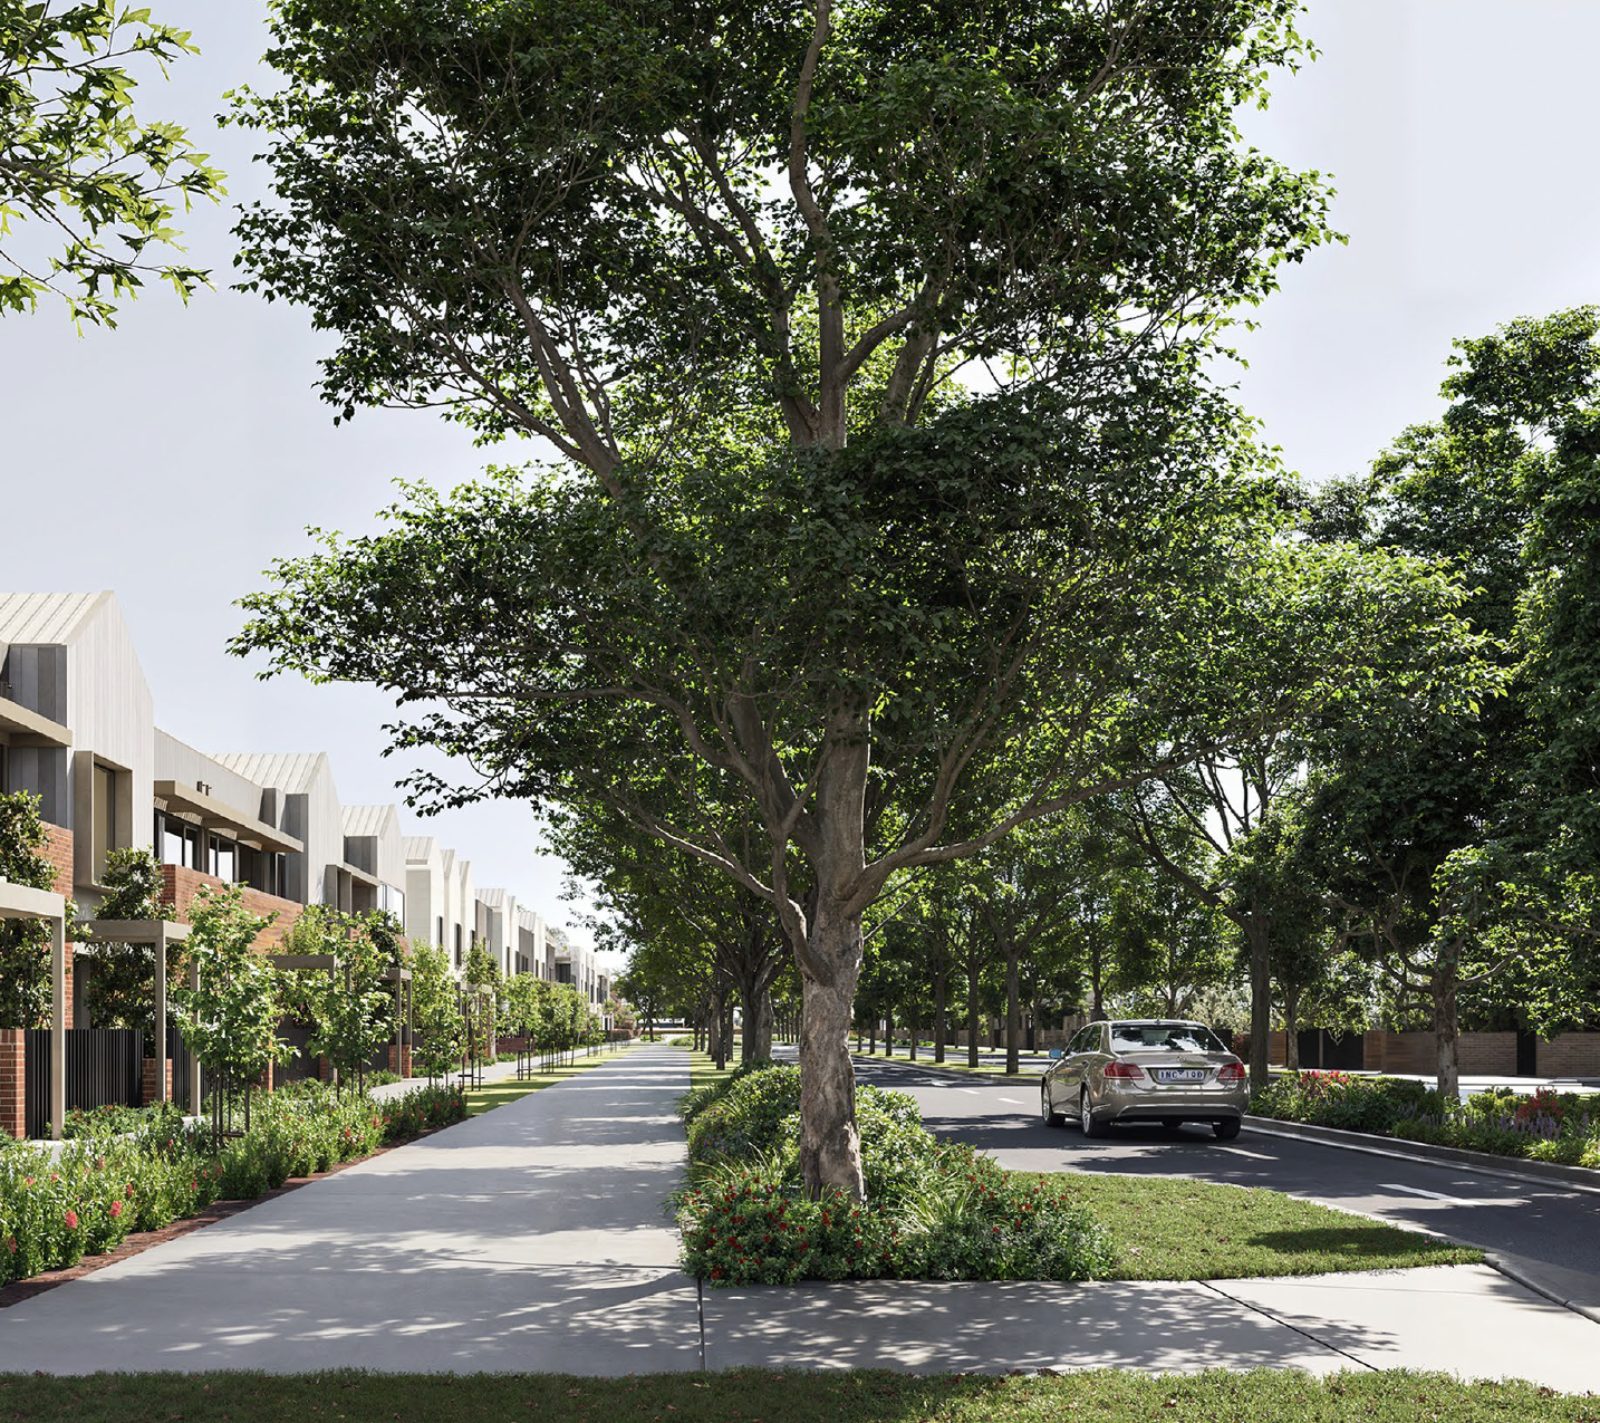
New amenity, inside a suburb where the schools, shops and freeway are already there. That is the combination a tenant pays for and an investor rarely gets at a new-build price.
Comprehensive Development Plan, Victorian Planning Authority. Figures are plan targets for the whole precinct, not for this release alone.
Oli Property is part of the Oliver Hume Property Group, which has sold Australian residential property since 1954 and helped over 290,000 Australians buy and invest in new property.
Our research, led by Chief Economist Matt Bell, covers 4,800 suburbs and is relied on by government and ASX 200 companies. Every property we put in front of a client has been through our 60 data point review process first.
We have no reason to push you toward one outcome over another, which is why we run the numbers against our 60 data point review process, across 4,800 suburbs. If this project does not suit your position, we will tell you, and we will tell you why.
The New-Build Investor's Toolkit is free, arrives by email, and is written to be read alongside your accountant. If you would rather talk it through first, a discovery session with Cam or Adam is about an hour by video.

About the figures on this page
The worked example figures are from the Oli Property Property Tax Changes guide, May 2026, and are illustrative only. The $850,000 figure is a release price for a three-bedroom townhouse, not a median, and is subject to written confirmation. Distances are straight line.
General advice disclaimer
The information on this page has been prepared as a general guide only and does not constitute advice. It has been prepared without taking account of your objectives, financial situation or needs. Before acting on any information you should consider its appropriateness having regard to your own objectives, financial situation and needs, and seek independent advice from a qualified professional. Any forward looking statements are estimates only, are affected by a significant number of unpredictable factors, and there are no guarantees they will be achieved. Property markets perform at different rates and past performance is not an indicator of future performance. Taxation outcomes depend on individual circumstances and you should speak with a qualified accountant.
Mortgage brokerage is provided by MyFirstLoan.au Pty Ltd ACN 168 808 946, Australian credit representative number 564038 of Allied Financial Consulting Pty Limited ACN 059 732 419, ACL 393845. Loans are structured and managed by Homestar Finance, ACL 390860.